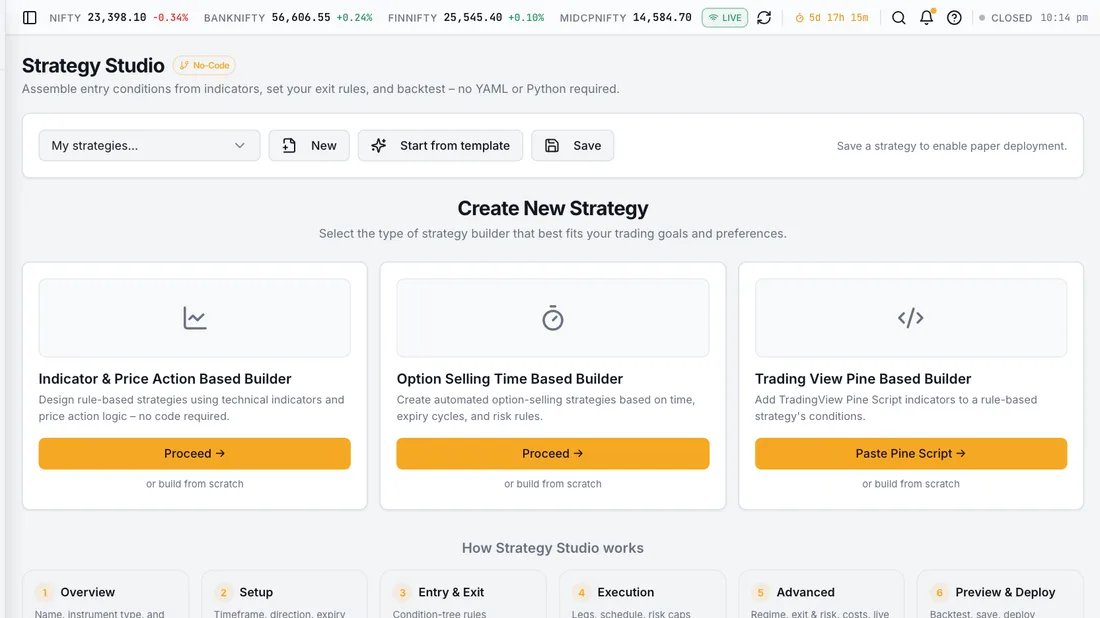
Built, not coded
Entry and exit as a condition tree, with the stop attached.
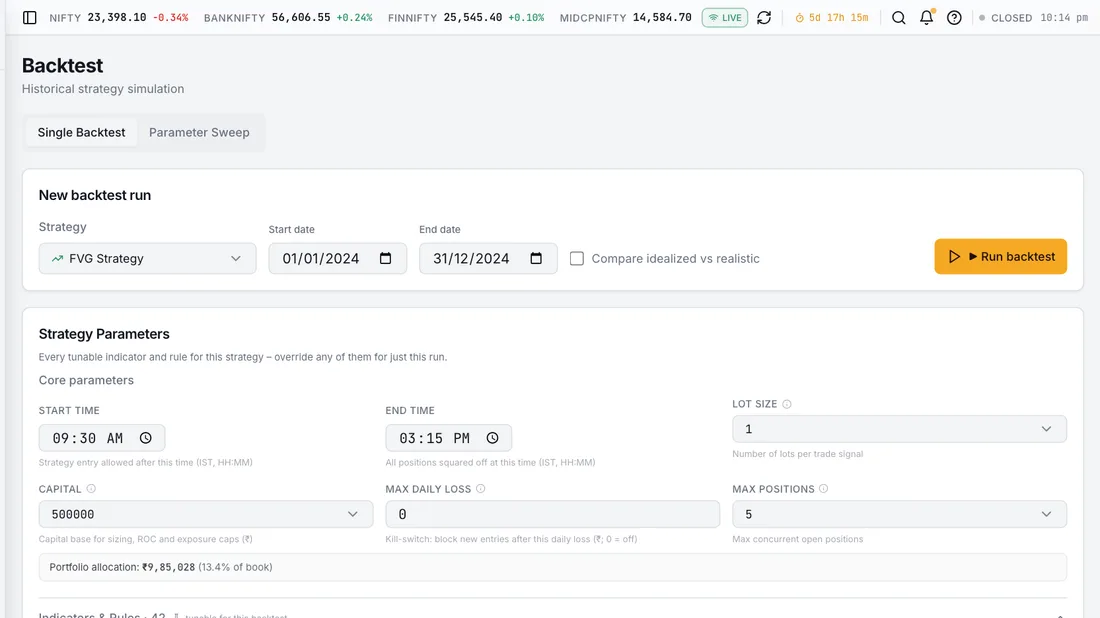
Backtested with costs
Brokerage, slippage and impact modelled – not a frictionless curve.
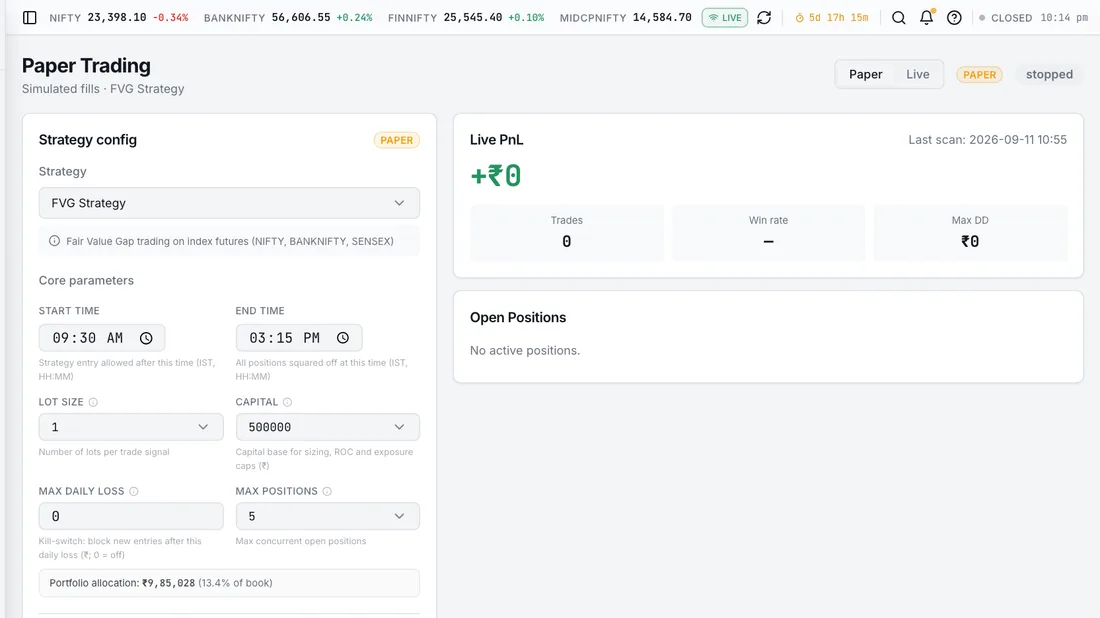
Then forward-tested
Recorded before the outcome is known, scored against real bars.
Algorithmic trading & backtesting
Backtesting Engine
Paper Trading
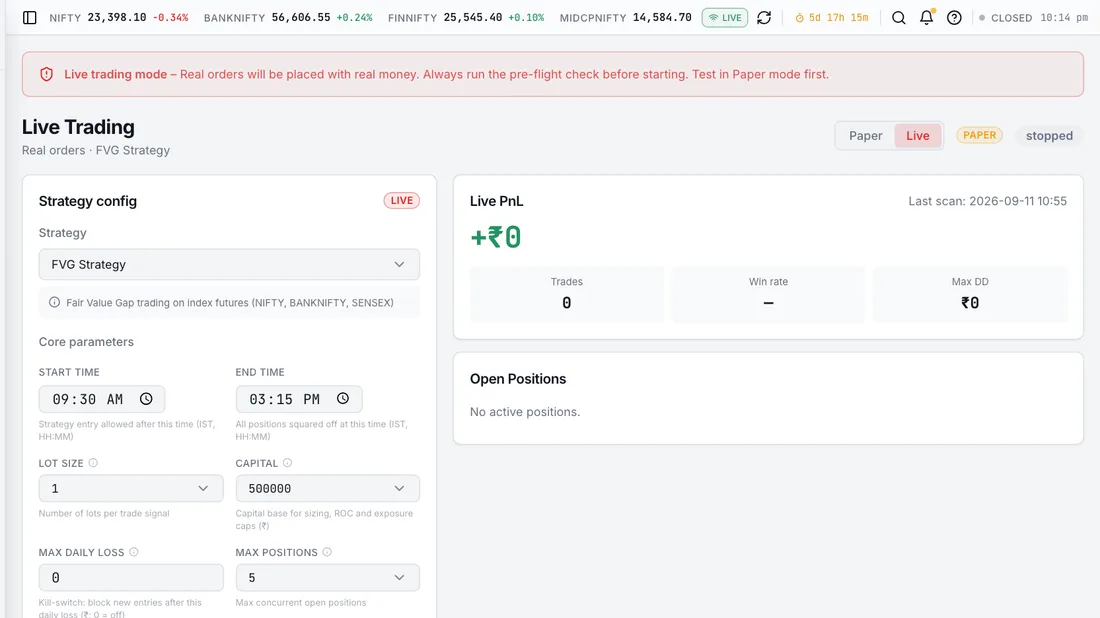
AlgoHub Live
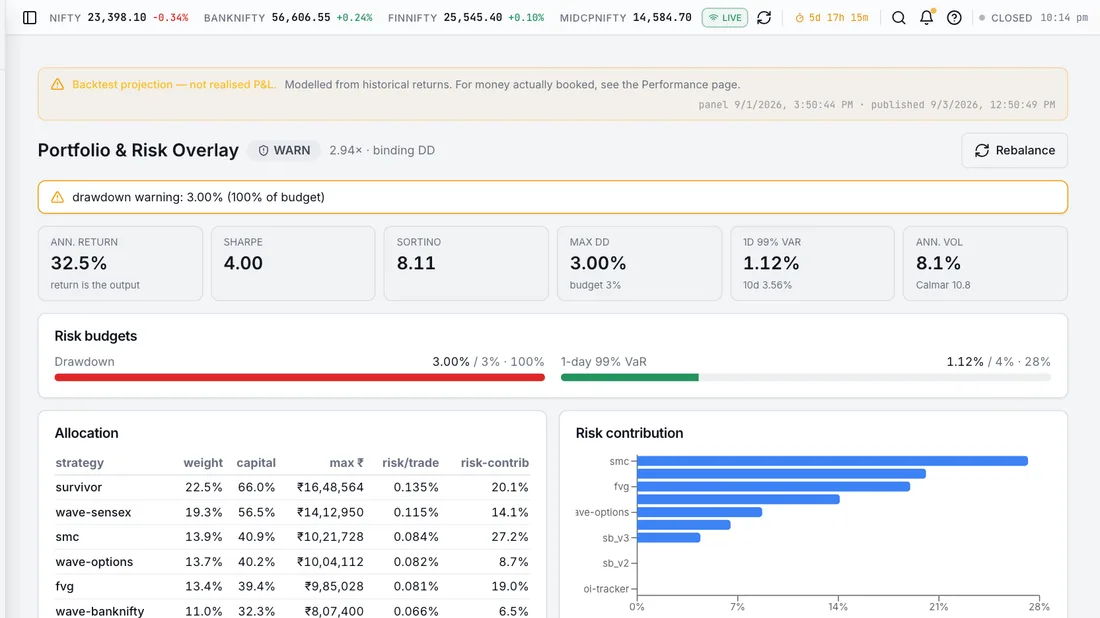
Portfolio & Performance

Mean Reversion · F&O Stocks

Wealth Planner

Smallcases
Order Audit Log
swipe to browse
Common questions
Do I need to write code?
No. Strategies are built as condition trees – indicators, comparisons and logic – and every one carries a stop.
Are costs included in backtests?
Yes: brokerage, slippage and impact are modelled. A frictionless backtest flatters a high-turnover strategy most, which is exactly where it misleads.
Is a backtest the same as a track record?
No. A backtest is fitted with hindsight; a forward test records each signal before its outcome is known. Both are shown, and they are labelled differently.